Economic Models for Calculating Damages in Tobacco Class Actions
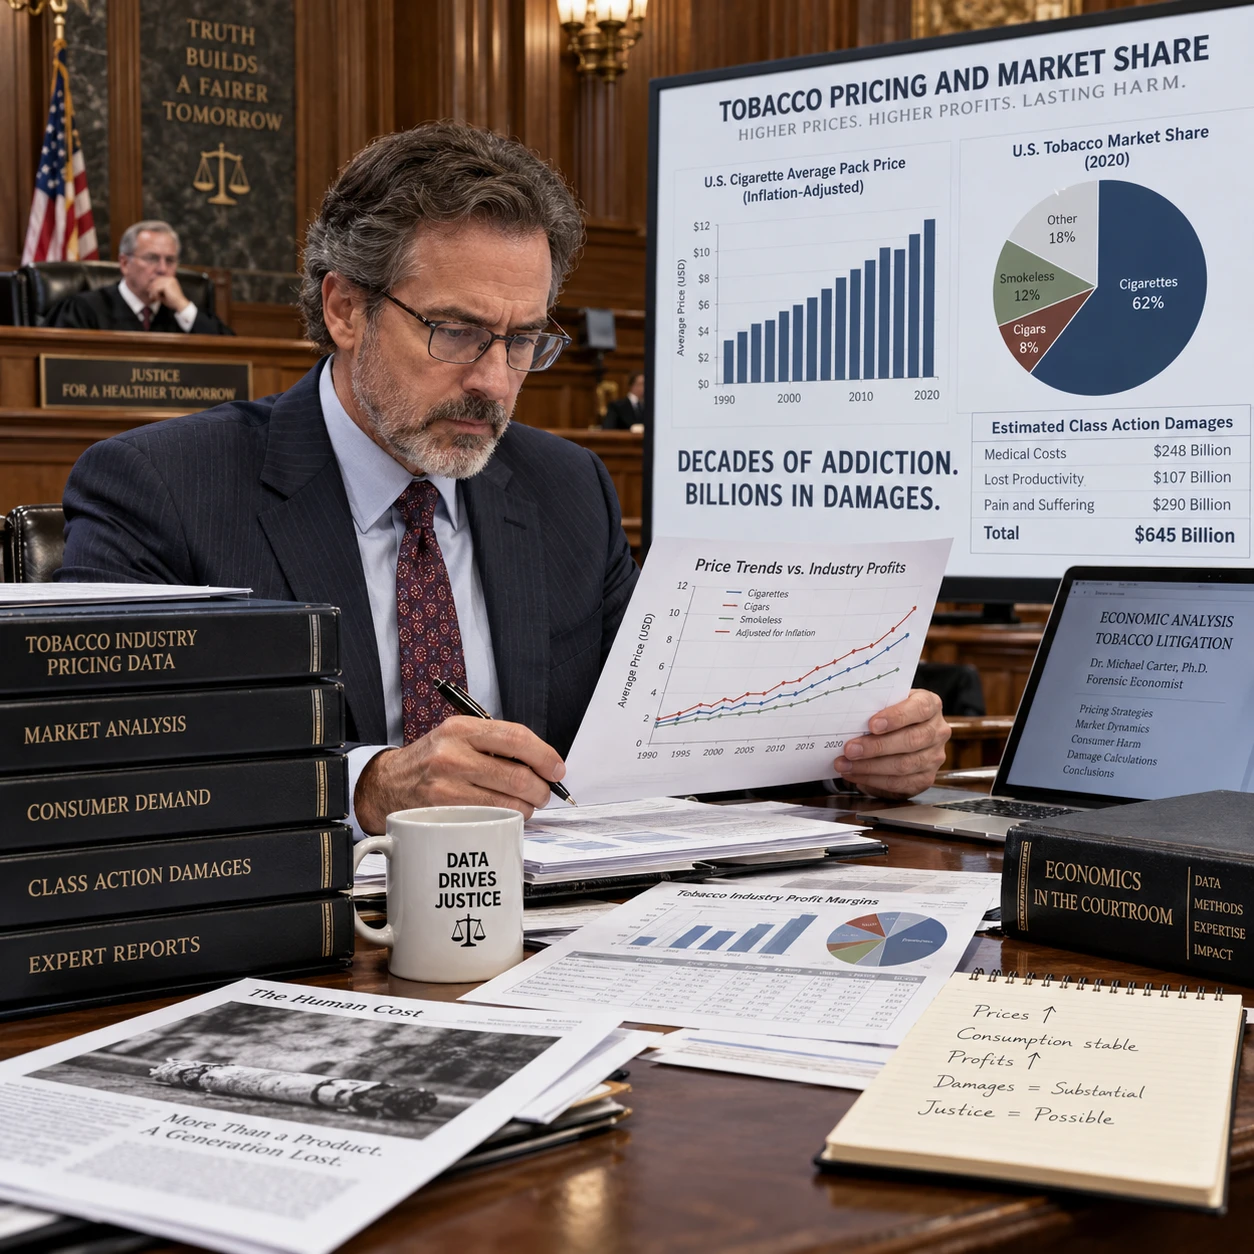
In tobacco litigation, a damages model translates an alleged economic injury into an estimate that can be tested against market evidence. Economists may examine whether consumers paid more for a tobacco product, received less value than represented, or suffered another legally recognized loss. The method depends on the claims and evidence; a model estimates harm, but does not by itself establish liability.
Why damages models matter in tobacco class actions
Economic damages models explain how alleged tobacco-related conduct could have caused measurable loss across a proposed class. They connect a legal theory to evidence about prices, product value, purchases, and the market conditions consumers faced.
An economic expert typically starts by identifying the alleged conduct and the claimed injury. For example, a case might allege that a product feature or marketing statement affected the price consumers paid. The expert then asks whether that effect can be measured using a consistent method for class members, rather than relying only on individual accounts.
This analysis can matter at more than one stage of a class action. A proposed model may be examined in connection with class certification, expert evidence, or the calculation of damages if liability is established. The court’s legal and evidentiary standards govern what proof is acceptable. A numerical estimate alone does not show that the conduct caused the loss, that the proposed class is appropriate, or that every consumer experienced the same injury.
The central question is whether the model fits the claim: What economic harm is alleged, and what evidence could measure it? If the method depends on individualized facts that vary substantially among buyers, that may create challenges for class-wide proof or allocation.
Defining the alleged injury and the counterfactual
A counterfactual is a reasoned estimate of what the tobacco market or transaction would have looked like without the challenged conduct. Comparing that scenario with observed conditions helps an expert estimate the economic difference attributed to the alleged conduct.
The expert first defines the claimed injury precisely. Did consumers allegedly pay an inflated price? Did the product deliver less value than promised? Is the claimed loss tied to a particular period, product line, or group of purchasers? These questions shape the model. A broad allegation without a clearly defined economic injury is difficult to translate into a reliable damages calculation.
The counterfactual market is not a directly observed alternative. It must be constructed from evidence and defensible assumptions. An economist might compare actual prices with estimated prices absent the conduct, using market data, comparable products, or changes over time. Each choice has limits. A comparison product may differ in meaningful ways, and a before-and-after comparison may capture other market changes along with the alleged conduct.
For instance, if an expert studies prices for a tobacco product during a period when a challenged representation was present, the analysis may need to account for taxes, manufacturing costs, competitor pricing, and broader demand changes. The point is not to assume those factors prove or disprove a claim. It is to separate the alleged effect from other plausible explanations as carefully as the evidence allows.
Common economic models for estimating loss
Common approaches include the price-premium model and the benefit-of-the-bargain model, but they measure different kinds of alleged injury. Other methods may be considered when they fit the claim, available evidence, and governing law.
Price-premium model
A price-premium model estimates whether consumers paid more because of the challenged conduct. The expert compares the observed price with a counterfactual price that is intended to reflect what the product would have cost absent that conduct. If the model estimates a per-unit premium, total loss may be calculated by applying it to eligible purchases, subject to the case’s legal rules and proof.
Economists may use regression analysis to estimate how prices relate to factors such as product characteristics, time, location, taxes, and competitive conditions. Regression can help isolate relationships in complex data, but it does not automatically establish causation. Results depend on the variables included, data quality, and whether the model reasonably reflects the market.
Benefit-of-the-bargain model
A benefit-of-the-bargain model estimates the difference between the value a consumer allegedly expected to receive and the value actually received. In a tobacco case, the expert would need to connect the claimed expectation or representation to a measurable difference in product value. That inquiry may require evidence beyond the product’s price.
These approaches are not interchangeable. A price-premium analysis asks whether the transaction price was higher than a modeled alternative. A benefit-of-the-bargain analysis asks whether the value delivered fell short of the value represented or expected. Depending on the claim and applicable law, one approach may fit better, neither may be supported, or another measure may be relevant. Choosing a model for simplicity can leave the alleged injury unmeasured.
Data and assumptions behind the analysis
Economic models in tobacco class actions may draw on pricing, sales, product, market, and consumer evidence. The assumptions used to interpret those records can matter as much as the volume of data collected.
Potential sources include retail or wholesale prices, transaction and sales records, product attributes, market shares, competitor prices, tax changes, and the dates and locations of sales. Depending on the claim, consumer surveys or internal business records may also be relevant. An expert must explain how the information relates to the alleged conduct and the class definition.
Data coverage is a practical constraint. A dataset might omit certain retailers, regions, product versions, or time periods. If purchases cannot be reliably identified, an aggregate calculation may require estimates that introduce uncertainty. Likewise, prices listed in a database may differ from prices consumers actually paid after discounts or promotions.
Assumptions should be visible and testable. An expert can examine alternative specifications, vary key inputs, and explain whether conclusions change. Sensitivity analysis does not remove uncertainty, but it can show which assumptions drive the result. A sound report distinguishes observed facts from modeled estimates and identifies what the available data cannot establish.
From individual claims to aggregate damages
Aggregate damages estimate losses for a defined group by combining class-wide evidence with a method for counting eligible purchases or consumers. Aggregation can simplify arithmetic, but it cannot cure a mismatch between the model and the injury claimed.
A simplified calculation might multiply an estimated per-unit loss by the number of qualifying units sold during the relevant period. The difficult work lies in defining qualifying transactions, excluding purchases outside the class, and deciding how to treat refunds, discounts, or different product versions. The calculation also needs to avoid counting the same alleged loss twice.
Class-wide proof asks whether common evidence can establish relevant elements for the group under the applicable legal framework. It does not necessarily mean every person experienced identical circumstances. But if individual factors—such as what a consumer saw, why they bought a product, or the price they paid—are central to the claimed injury, the expert and the court may need to assess how those differences affect the method.
Aggregation also differs from allocation. An aggregate figure estimates the group’s total modeled loss; allocation addresses how any recovery would be distributed among eligible claimants. The two tasks can require different information. A class-wide total may be statistically estimable even when determining each member’s share requires purchase records or another claims process.
Testing a model’s limits and legal fit
A damages model must match the alleged injury, account for causation and allocation, and comply with the governing legal framework. Its limitations should be stated clearly, because precision in a spreadsheet does not eliminate uncertainty in the evidence.
Causation is a key test: does the analysis isolate the economic effect attributed to the challenged conduct, or could other factors explain the difference? The expert should address plausible alternatives, data gaps, and the effects of changes in taxes, costs, competition, or consumer demand. The answer may remain uncertain, and a court determines the legal significance of that uncertainty.
Allocation raises a related question: can the estimated loss be assigned to the conduct and to the relevant class members without including unrelated purchases or harms? The model also needs to fit the specific claims and remedies available under applicable law. A method used in one tobacco case may be unsuitable in another because the alleged conduct, products, time periods, evidence, and legal theories differ.
A useful review framework is to ask three questions: Is the injury defined? Is the counterfactual supported? Can the estimate be tied to eligible transactions and the alleged cause? A weak answer at any step signals a limitation for the expert to explain, not a gap to hide with a larger dataset. Ultimately, damages analysis is one part of a broader case; it does not substitute for proof of the underlying legal elements.
Frequently asked questions
What is a price-premium model?
A price-premium model estimates how much more consumers allegedly paid than they would have paid without the challenged conduct. It relies on a supported counterfactual price and evidence about relevant purchases.
How are damages estimated for an entire class?
An expert may estimate loss per purchase or consumer and combine it with records of eligible class transactions. The method must address the class definition, data coverage, and differences that could affect the claimed injury.
Why do economists use a counterfactual?
The counterfactual provides a comparison: estimated market conditions without the alleged conduct versus observed conditions. Because that alternative cannot be directly observed, the expert must justify the evidence and assumptions used to construct it.
Can one damages model apply to every tobacco class action?
No. The appropriate model depends on the alleged conduct, claimed injury, available evidence, class-wide proof requirements, and governing law. A method suitable for a price-inflation claim may not measure a different theory of loss.